
Quick answer: inspection or appraisal?
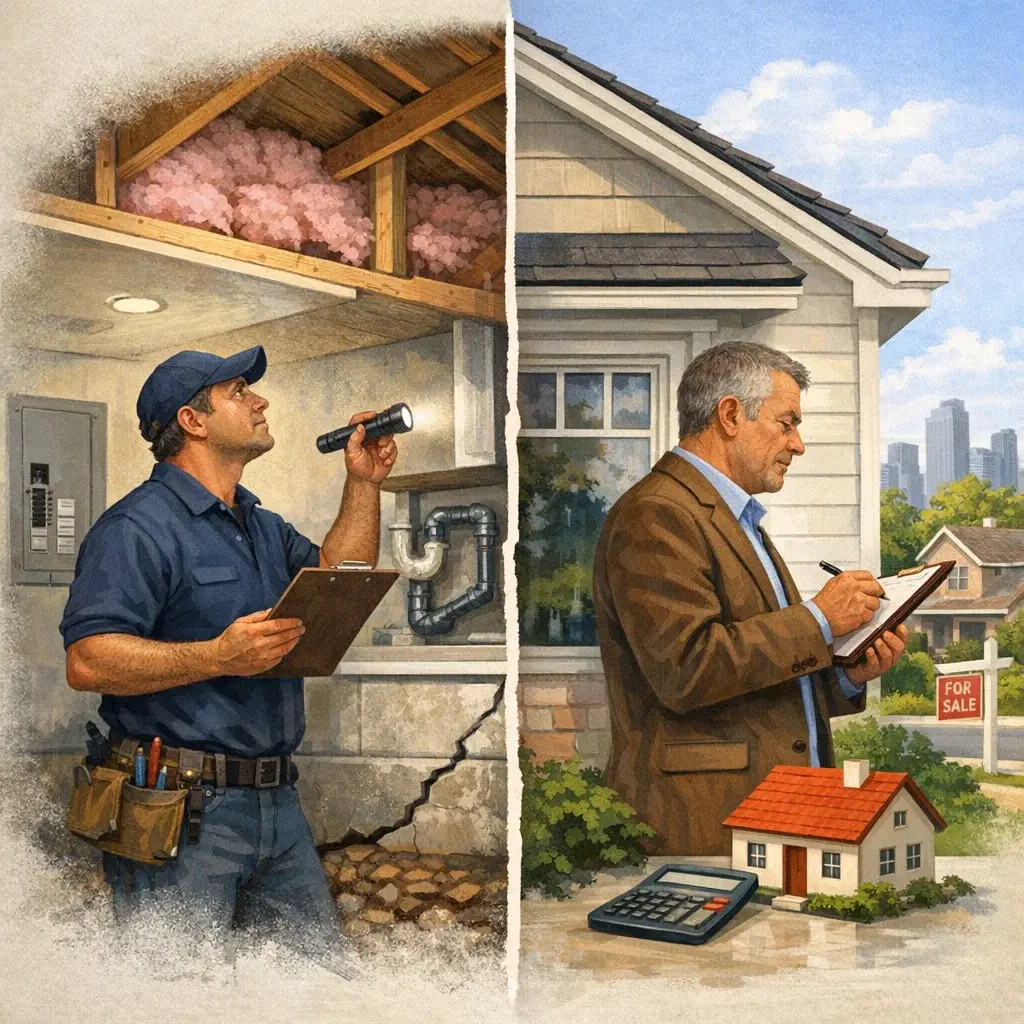
A home inspection looks at the visible condition of a property. An appraisal estimates a property's value for a stated purpose, often to help a lender assess mortgage security. An appraisal is not a full home inspection, and an inspection is not a market valuation. A buyer may need both for different reasons.
What a home inspection is designed to answer
A licensed inspector reviews accessible systems listed in the inspection contract. These may include the exterior, roof, structure, plumbing, electrical components, heating, ventilation, and the interior. The written report describes visible conditions, concerns, and areas needing expert advice.
The main buyer question is: What might this home need, and what remains unknown? A report can note a damp basement wall, aging roof materials, or an unsafe electrical condition. It does not certify hidden systems or promise a repair budget.

What a property appraisal is designed to answer
An appraisal develops an opinion of value based on its assignment. An appraiser may consider comparable sales, location, property type, market conditions, size, and other features. The appraisal's purpose, intended user, and methods matter. A lender often orders one to help decide whether the property supports the requested loan.
An appraiser might notice obvious condition issues, but that does not turn the appraisal into a detailed systems check. A home can have an appraised value near its purchase price and still need major work. Equally, an inspection with few visible defects does not prove the offer price reflects market value.
Who usually arranges and receives the report?
Buyers often hire a home inspector for their own due diligence and receive the inspection report under their contract. A lender may arrange an appraisal through its own process, though fees can be charged to the borrower. Ask your mortgage broker or lender who orders the appraisal and whether you will receive the full report.
Do not assume the lender's valuation report protects you from every repair. The lender's main concern is whether the loan is supported by the property. The buyer has a wider concern: comfort, safety, ongoing costs, and fit for their life.
A side-by-side example
Imagine a townhouse in Coquitlam with a purchase price of $900,000. An appraisal might compare similar recent sales and assess whether the value supports the financing request. The inspection might find a bathroom fan problem and signs of moisture by a balcony door. Both results can be true at the same time. With attached homes, a townhouse inspection can also clarify accessible conditions and limits around shared components.
The buyer should use the inspection finding to ask for repair history or specialist advice. The lender may separately review the appraisal and loan approval. Neither report answers every question about the other.
Why a low appraisal is different from a bad inspection
A low appraisal may change the financing discussion because the lender might not base the loan on the full agreed purchase price. A concerning inspection may change how the buyer sees future repairs and risk. Each issue needs a different professional conversation. New buyers may find the first-time home buyer inspection guide useful.
For value or financing questions, speak with the lender, broker, and real estate professional. For property defects, speak with the inspector and relevant trades. If either issue may affect a subject clause, talk to your real estate professional or lawyer quickly about the exact contract.
Do appraisal and inspection have overlapping areas?
There can be some overlap because property condition affects value and ownership risk. Both professionals may visit the property or review information about it. But the level of detail is different. An appraiser is not expected to test every accessible plumbing fixture simply because it affects a house's value.
Likewise, an inspector does not compare sold properties to decide market value. BC's home inspection guidance says the inspection is visual and aims to reduce risk, not remove it. Using one report for the wrong job creates false confidence. For local availability and coverage, review Coquitlam home inspection services.
What about strata condos?
For condos, an appraiser may consider market sales and unit characteristics. A home inspector reviews visible unit condition within scope. The buyer should also review Form B, financial records, bylaws, minutes, and the latest depreciation report if one exists. Shared repair costs are not fully explained by either a suite inspection or a valuation alone. For strata-unit purchases, a condo inspection can help document accessible in-suite conditions alongside separate strata-record reviews.

Buyer checklist before removing subjects
Confirm whether your lender requires an appraisal; ask about its timing; book the home inspection; review the findings; follow up on material risks; read strata records when applicable; and keep all financing and inspection conditions on a clear calendar. A mortgage pre-approval is not the same as final property approval. For the final decision, use the home inspection checklist before subject removal.
What to do if the two reports cause different concerns
Suppose the appraisal supports the agreed price but the inspection shows a leak. The lender may still review financing, while the buyer needs to understand the leak's cause and cost. Ask a roofer or other specialist for more detail; do not ask the appraiser to certify the repair.
Now suppose the inspection has few major findings, but the appraisal comes in below the offer price. A safe, well-kept home can still be overpriced compared with similar sales. That is a financing and valuation question to discuss with your lender or broker.
Keep both tracks on the same calendar. A financing subject and an inspection subject may have different requirements or deadlines. Ask a qualified adviser what each condition means in your actual purchase contract. For a property purchase, a pre-purchase home inspection can document accessible conditions before the buyer makes a decision.

Bottom line
Use an inspection for condition and an appraisal for value. If the purchase is important, do not ask either report to replace the other. For a broader view of home inspection services in the Lower Mainland, visit ENG Inspections.
Frequently asked questions
Can an appraisal replace a home inspection?
No. An appraisal aims to estimate value, while an inspection reviews visible property condition under a defined contract.
Does a mortgage lender require a home inspection?
Requirements vary by lender and property. Buyers may still choose an inspection to understand repair risk even if a lender does not require one.
Can a house pass inspection but appraise low?
Yes. The home can have few visible defects and still have a value opinion lower than the agreed price.
Will the appraiser find hidden water damage?
Do not rely on that. Even a home inspection cannot see every hidden issue. Specialist testing may be needed.
Sources and further reading
Official sources support the regulatory and buying-process information above. This article is general education, not a property assessment, legal advice, or a warranty promise.